4-Point Inspections in Orlando & Central Florida
A 4-Point inspection verifies the age and condition of your electrical, HVAC, plumbing and roof for your insurance company. If the home is older than 20 years, most insurers require one. Permit records are included with every report.
- Electrical
- HVAC
- Plumbing
- Roof
- Permit Records Included
What Is a 4-Point Inspection?
A 4-Point is an inspection required by insurance companies. It verifies the age and condition of four systems — electrical, HVAC, plumbing and roof — and tells the insurer how much risk they may be taking by covering the home.
Requirements vary between insurance companies, but if a home is older than 20 years a 4-Point is typically required. All of our reports include the permit records insurers ask for, pulled from county records.
Insurers want a full picture of the age and condition of these components, and photos must be included with every 4-Point form. If deficiencies are found, the insurer may require repairs, apply a larger deductible or higher premium, or deny coverage entirely.
Who Needs One?
- Almost every home buyer purchasing a home
- Homeowners renewing their annual insurance policy
- Homeowners changing insurance companies
- Homeowners who have made upgrades to the home may benefit from one
Who Does Not?
- New construction homes are typically not required to have a 4-Point
- Homeowners who already have a policy in place with a valid 4-Point report on file
What We Need Access To
During a 4-Point we inspect and photograph the following:
- Dwelling — each side of the home
- Roof — each slope
- HVAC — interior and exterior unit with data labels
- Plumbing — water heater, under kitchen and bath cabinets, drains, supply valves, wash machine and refrigerator connections
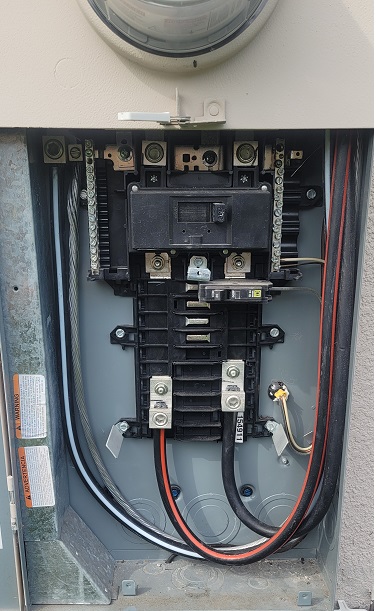
- Electrical — main and sub panels, interior and exterior, with label visible and cover removed
- All hazards or deficiencies in each of these categories
What Insurers Look For in Each System
1. Electrical
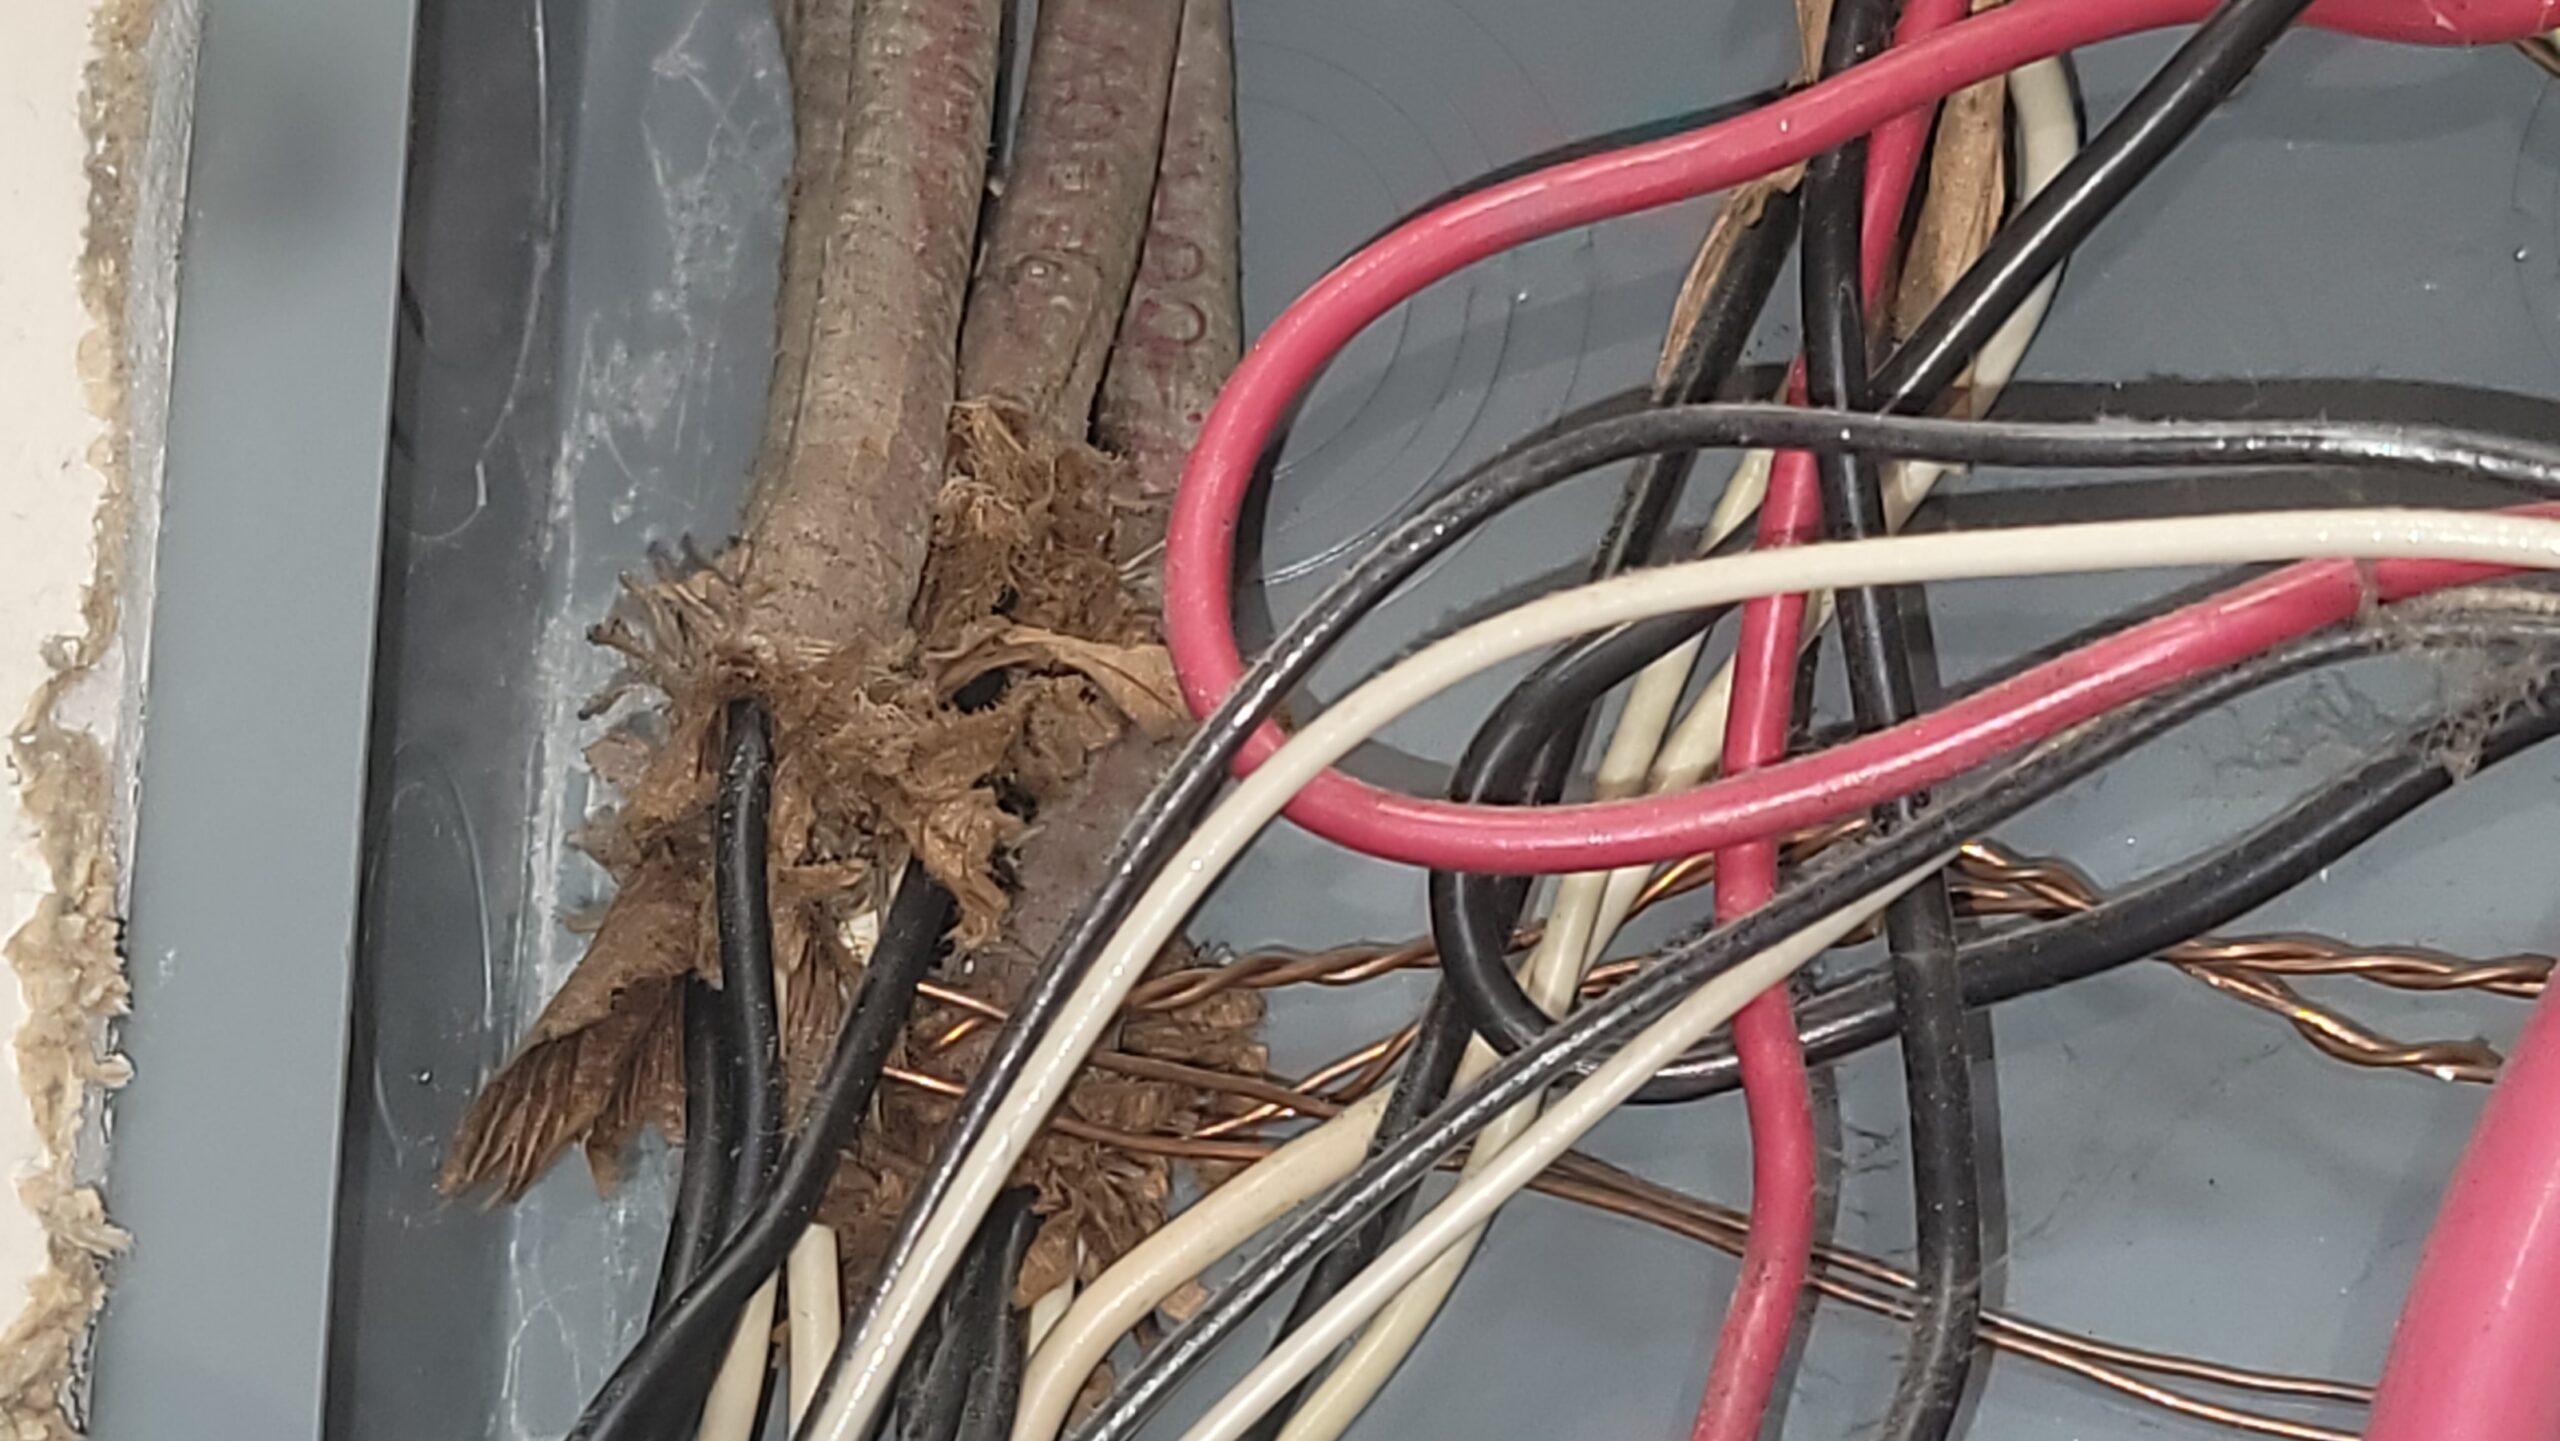
We photograph the panel with the cover removed and installed, and record amperage capacity, brand, age and wiring types. These commonly cause problems with insurers:
- Cloth wiring — usually homes built 1920–1975
- Active knob and tube wiring — usually 1920–1950
- Aluminum wiring (single strand) — usually 1965–1972. Read our aluminum wiring guide →
- Damaged or incorrectly sized breakers
- Exposed wiring and double-tapped breakers
Any of these will have to be repaired or replaced.
Problem Panel Brands
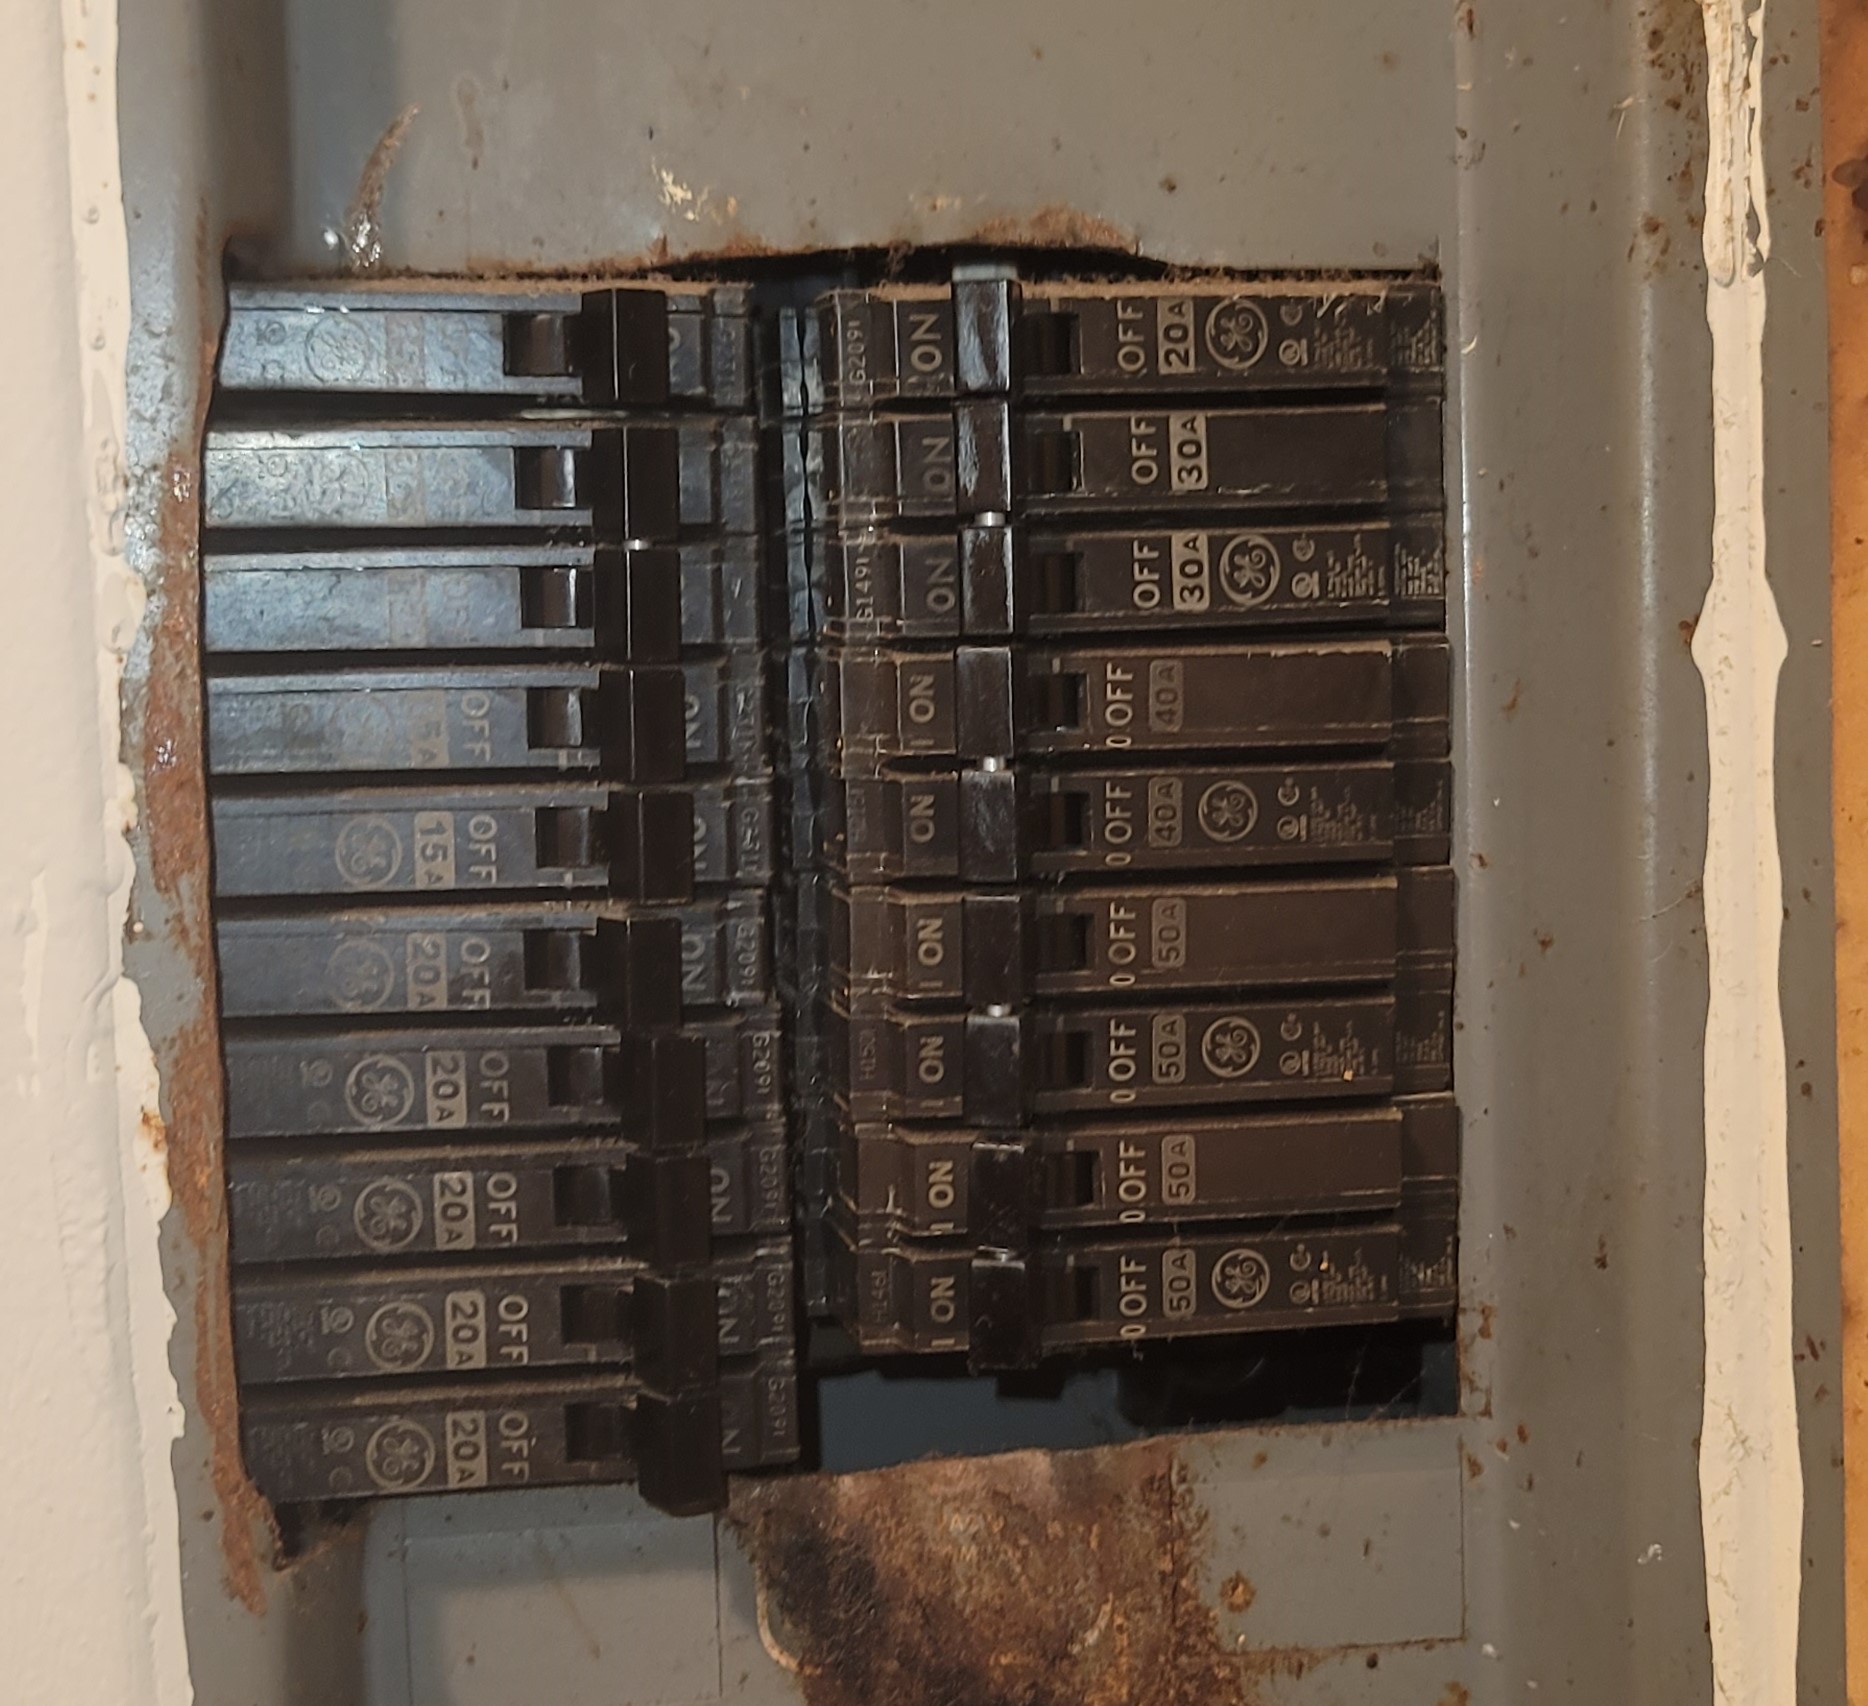
Known problematic panel brands are an issue for insurers. Watch for:
- Federal Pacific (aka FPE, Stab-Lok) — produced 1950–1980
- Zinsco
- Sylvania — produced 1973–1982
- Challenger — produced 1980–1995
If any of these are found during the inspection, they will likely need to be replaced.
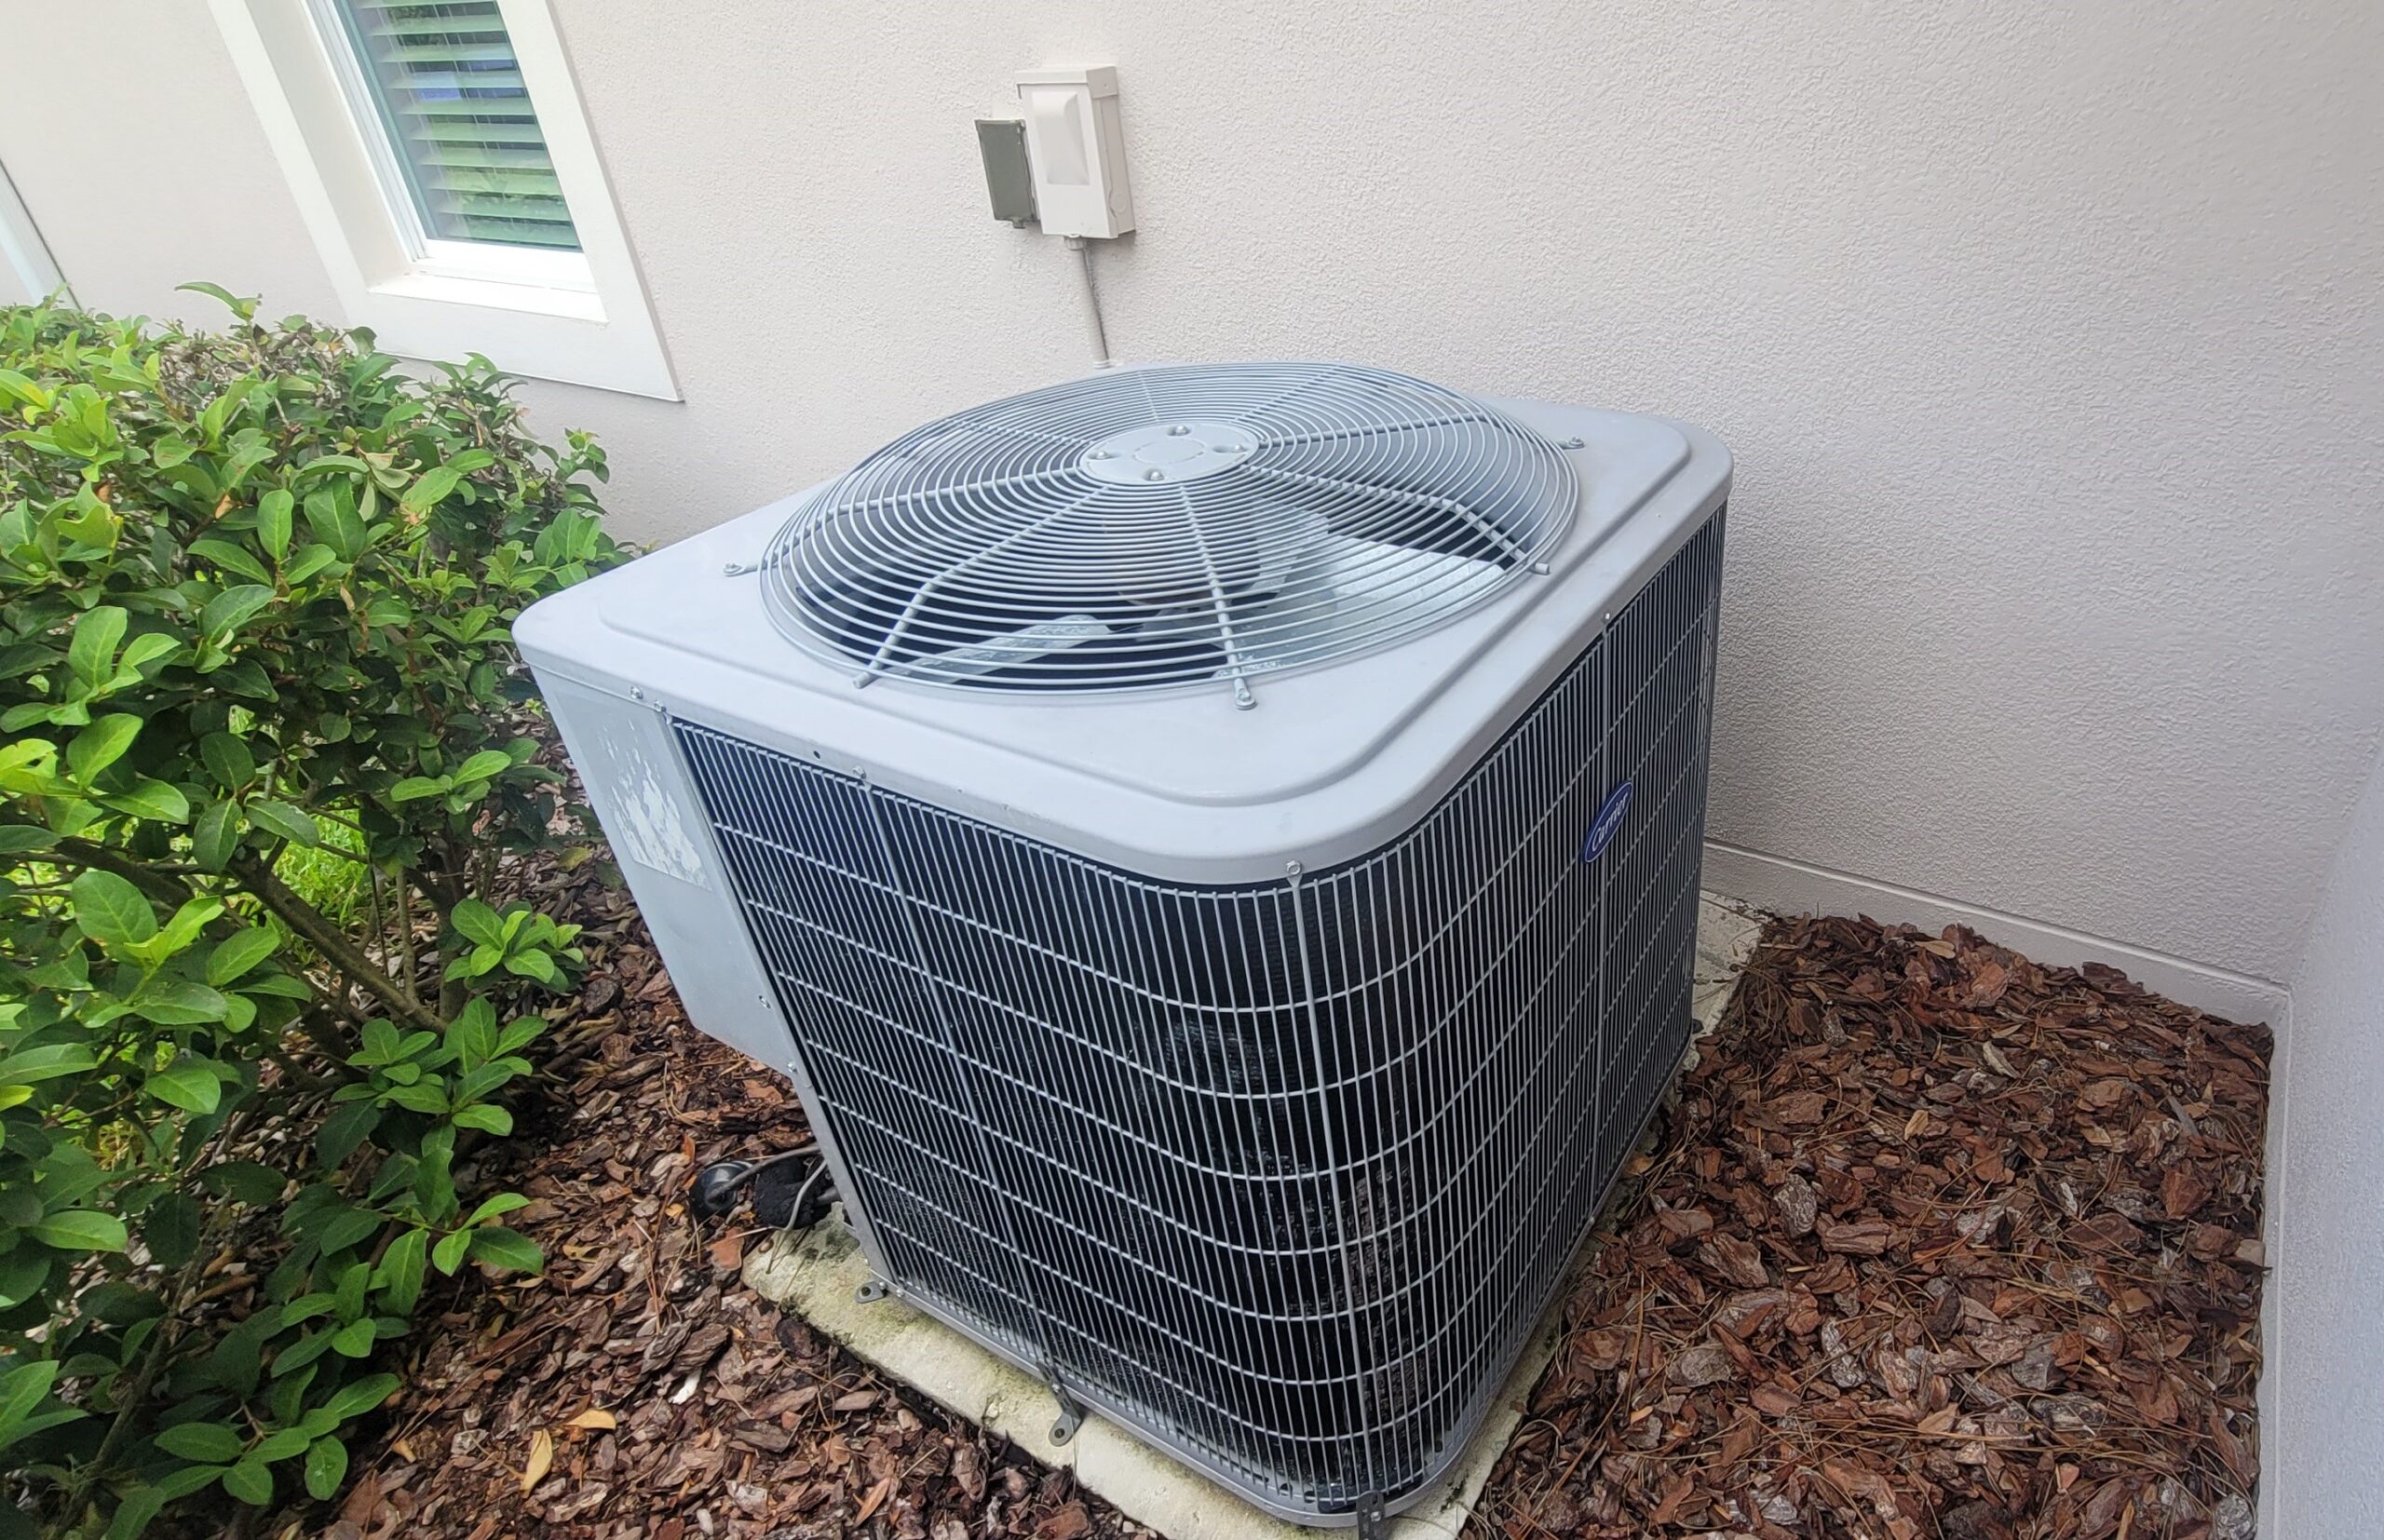
2. HVAC
The HVAC section is fairly simple. We inspect and report on:
- Presence of a wood-burning stove, gas fireplace or space heater
- Age and functionality of the unit
- Condensation drain line blockage or water damage around the unit
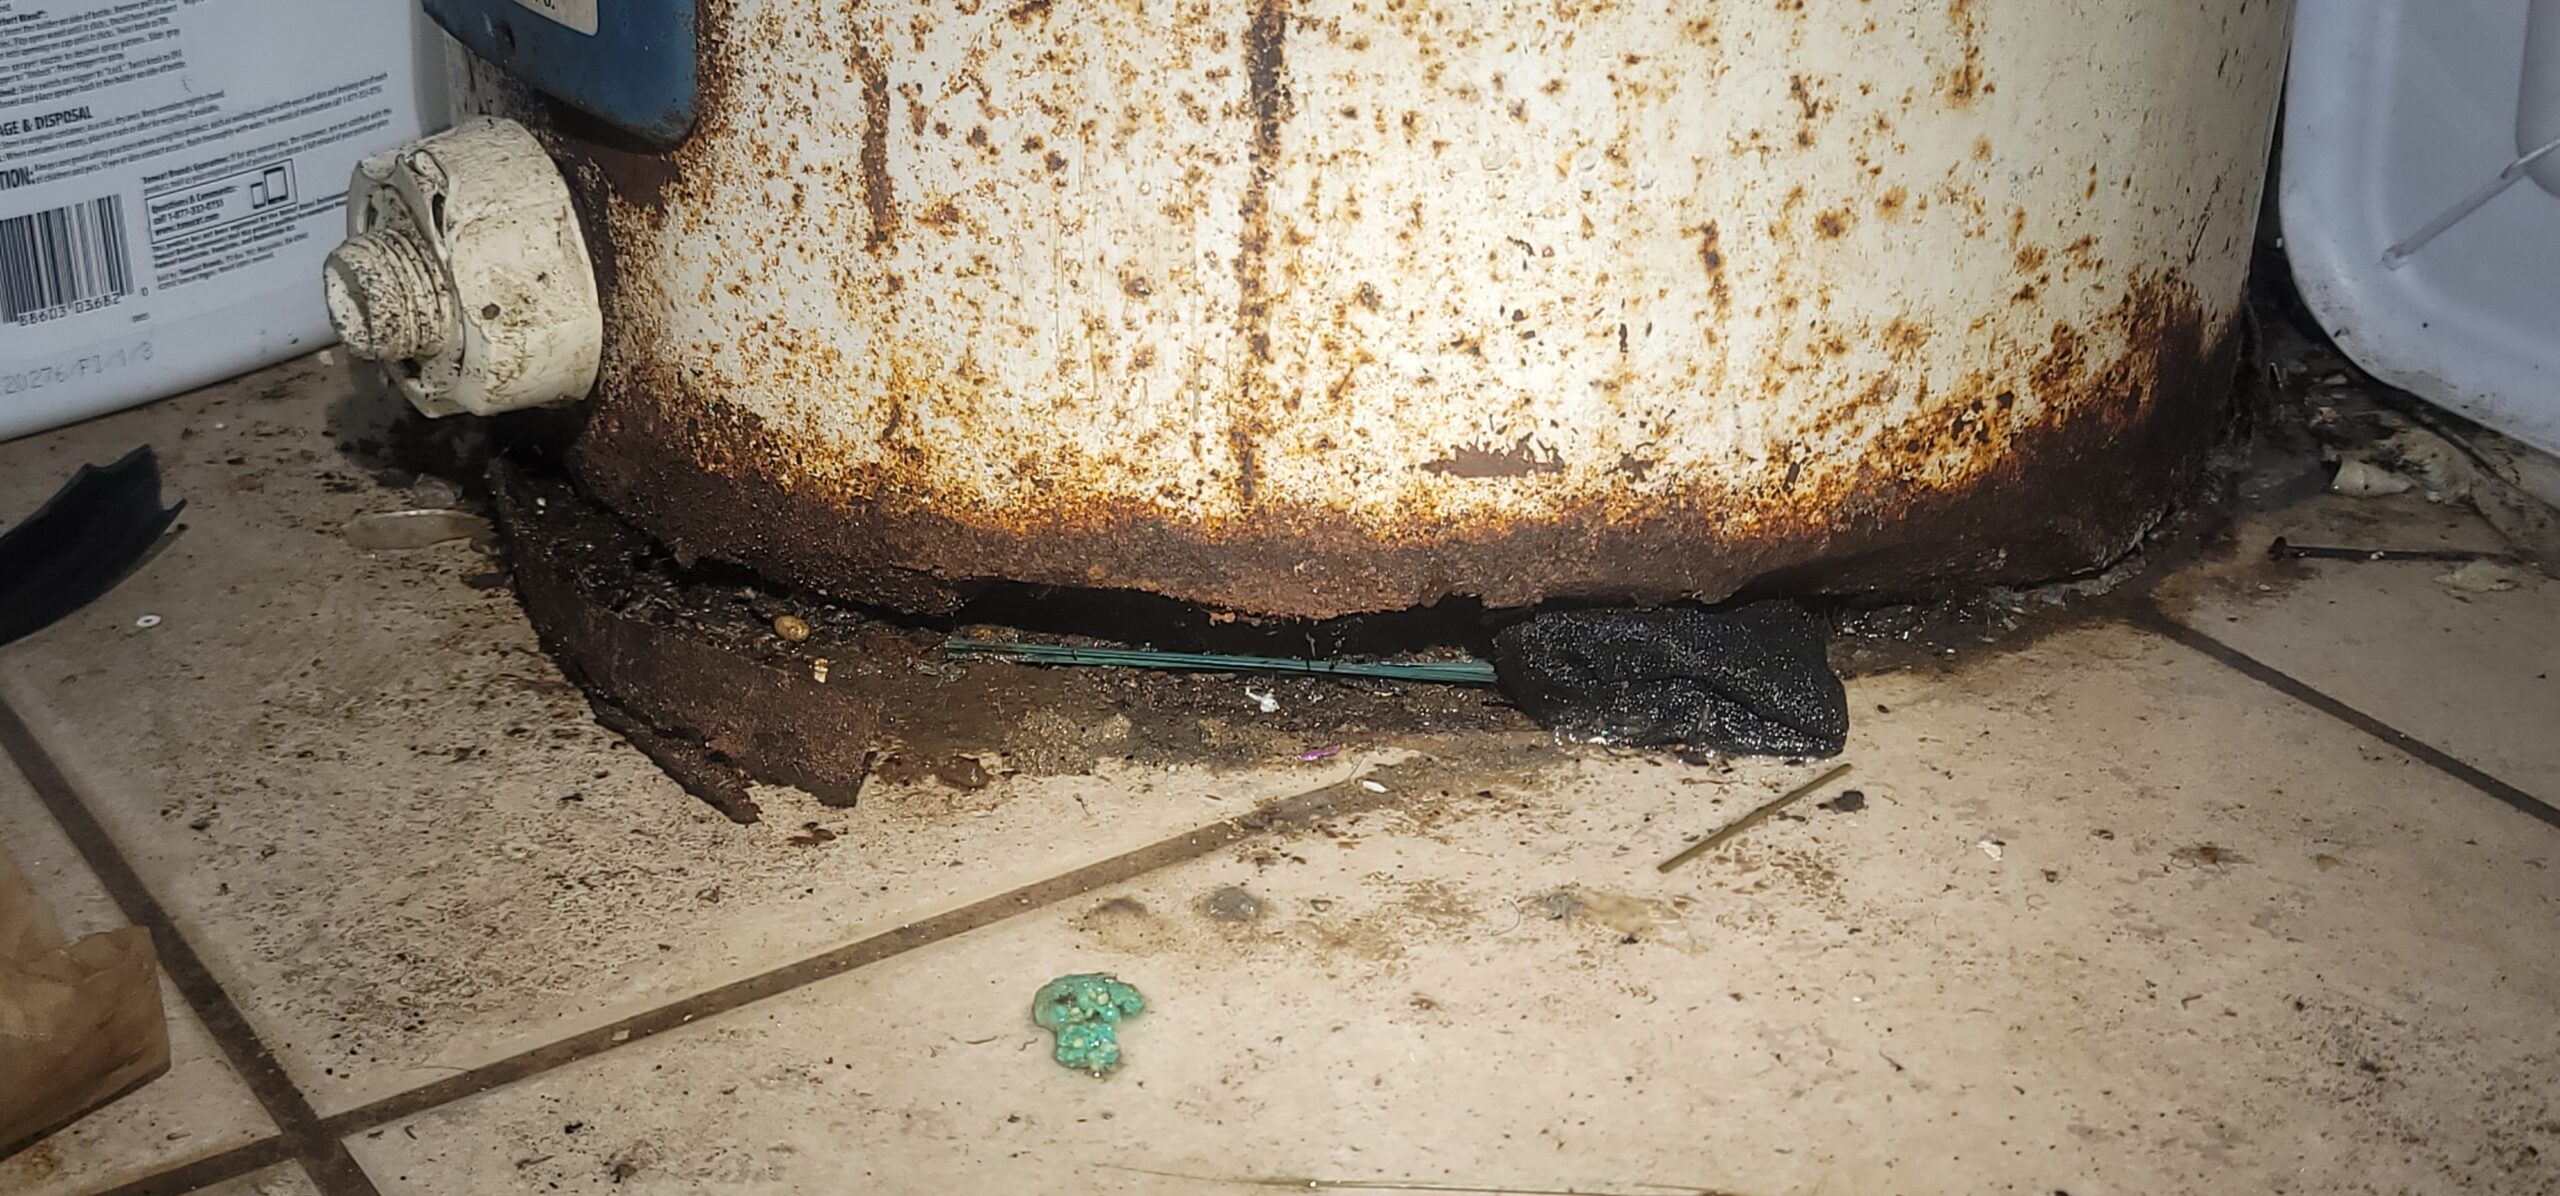
3. Plumbing
We inspect dishwasher and refrigerator connections, under kitchen and bathroom sinks, toilets and bathtubs, wash machine connections, water valves, sump pump, and the age and type of piping.
The water heater is the biggest component. Severely rusted, leaking, or simply old (over 20 years) is an issue for the insurer. A missing or damaged drain pan is a concern where a leak would damage the home.
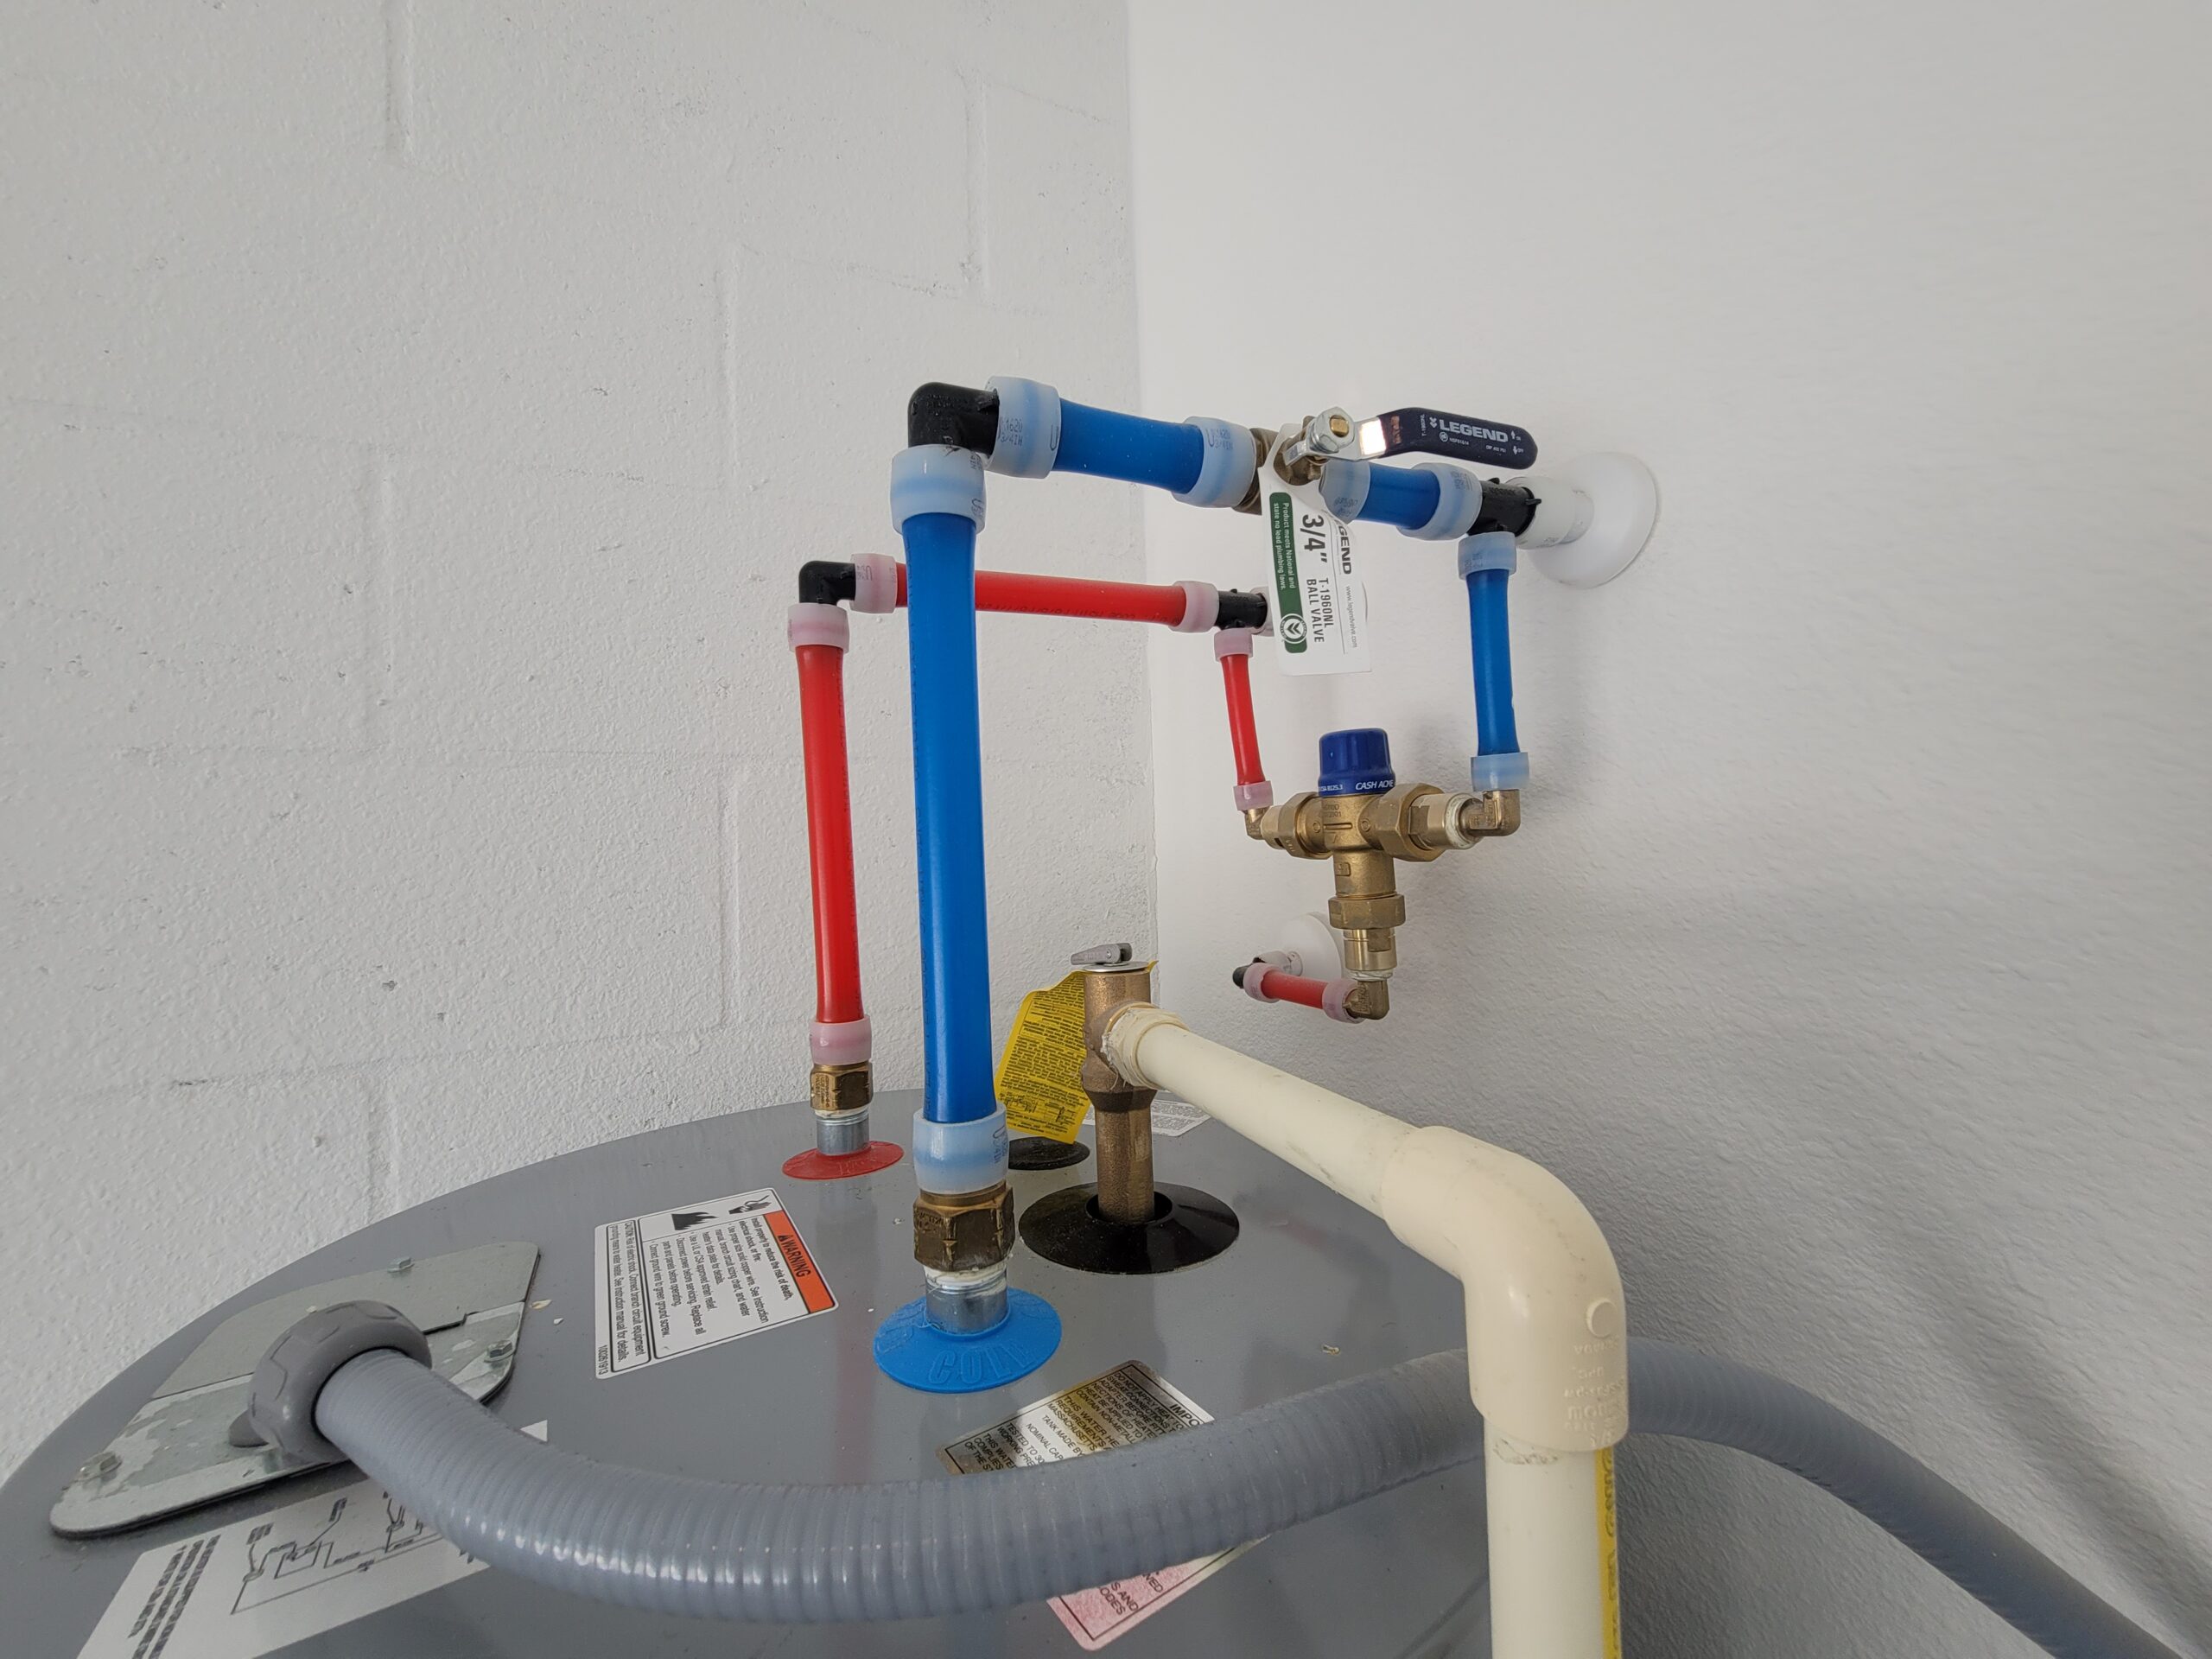
The pressure relief valve must have a drainpipe of approved ¾” material — copper, PEX or CPVC — extending within six inches of the floor or terminating outside.
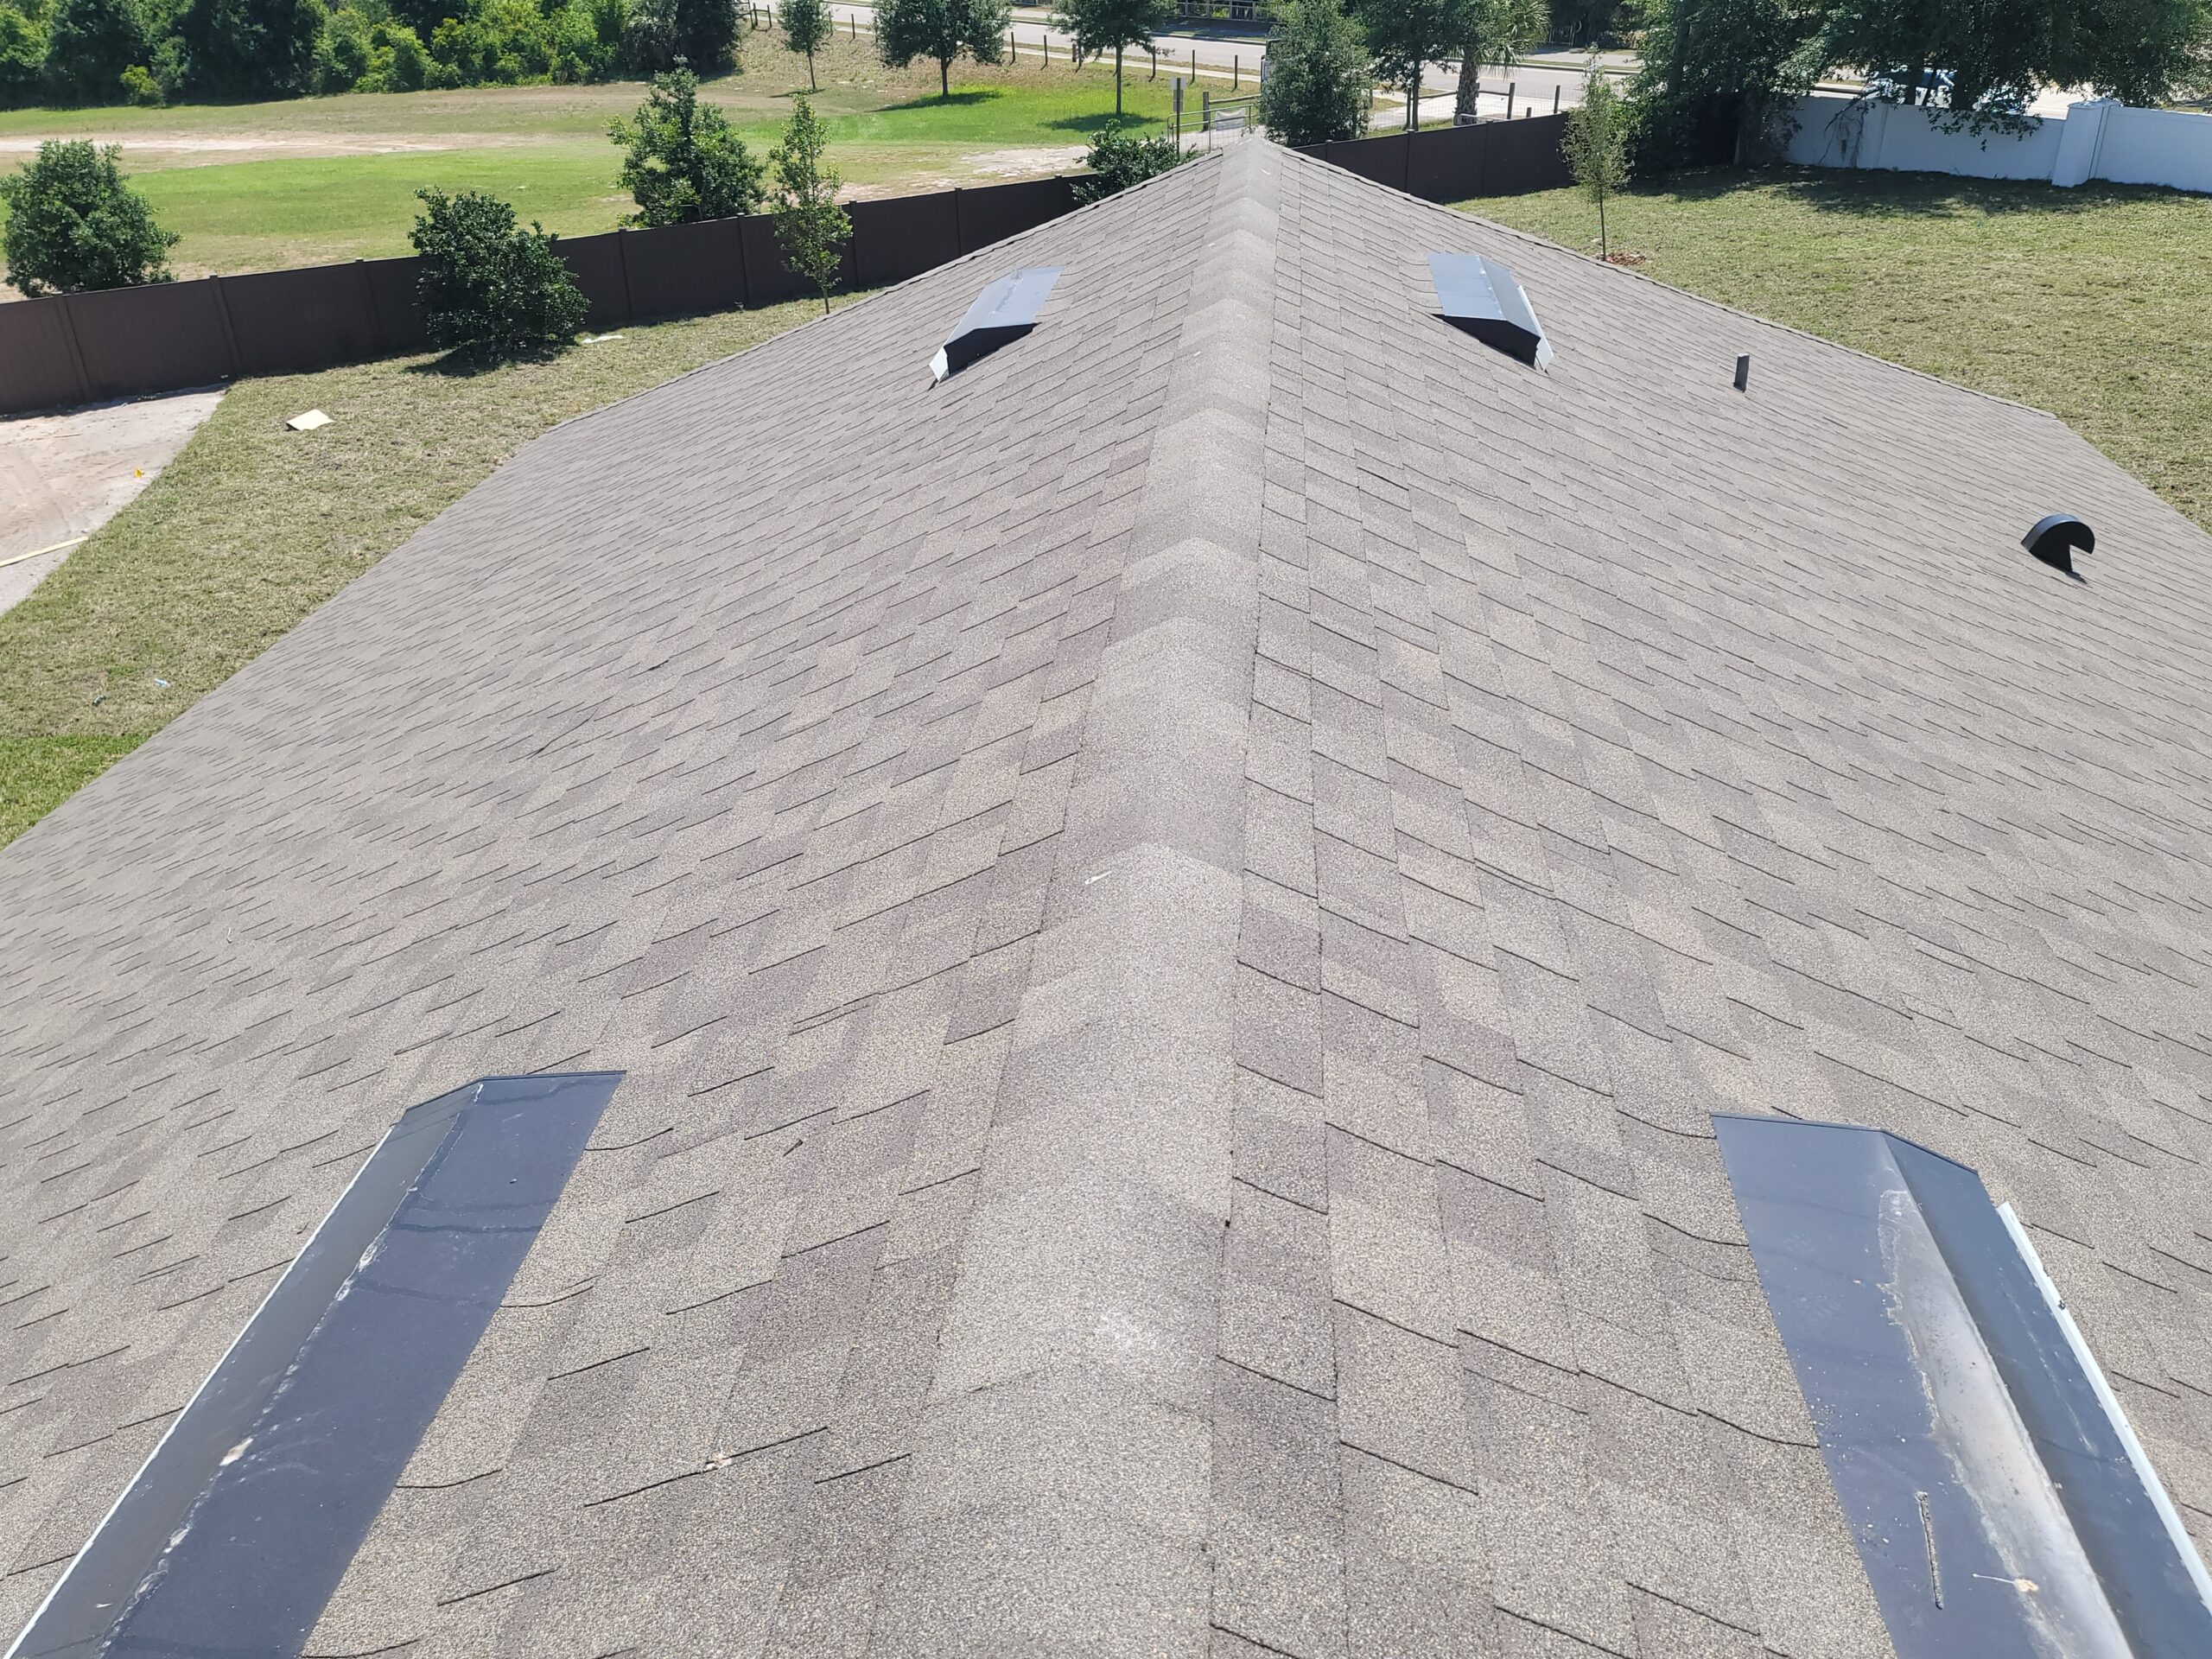
4. Roof
We inspect and report the type of roof covering — 3-tab, architectural, rolled, metal or tile — the condition and any defects observed, and the age of the roof, verified by the most recent county permit or contractor invoice, along with estimated remaining useful life.
The roof is the biggest concern to both the insurer and the homeowner, because it is the most expensive component on a 4-Point inspection.
A Note on Polybutylene
Most homes are plumbed with copper, PEX or CPVC. Some have polybutylene — a problematic pipe known for causing major water damage through leaks, manufactured and available to builders from 1978 to 1996.
If polybutylene is found during a 4-Point, expect the insurer to require replacement. Read our full polybutylene guide →
Common Questions
When is a 4-Point inspection required?
Requirements vary by insurer, but if a home is older than 20 years a 4-Point is typically required.
How long is a 4-Point report good for?
The 4-Point report is good for the life of the insurance policy. If you change insurance companies, the new insurer will not honor the previous report. If upgrades are made, a new 4-Point could benefit the homeowner.
How much does a 4-Point inspection cost?
A 4-Point is $200 stand-alone, or $100 when added to a home inspection. A 4-Point and Wind Mitigation combo is $250. See full pricing.
What happens if my 4-Point finds problems?
Private insurers may deny coverage for significant issues found on a 4-Point. Citizens will insure any homeowner, but it is a last-resort, state-backed insurer and a Citizens policy will cost more than a private one. We recommend working with a non-captive insurance agent or broker before turning to Citizens.
What if my home has polybutylene plumbing?
Expect the insurer to require replacement. Polybutylene was manufactured from 1978 to 1996 and is known for causing major water damage. Read our polybutylene guide.
Which electrical panel brands cause insurance problems?
Federal Pacific (FPE / Stab-Lok, 1950–1980), Zinsco, Sylvania (1973–1982) and Challenger (1980–1995). If found, they will likely need to be replaced.
4-Point Inspections Across Central Florida
We perform 4-Point inspections throughout Orlando, Kissimmee, St. Cloud, Celebration, Winter Park and Sanford — up through Daytona Beach and DeLand — and all along the Space Coast in Melbourne, Palm Bay, Cape Canaveral, Cocoa, Merritt Island and Titusville. Serving Orange, Osceola, Lake, Volusia, Brevard, Seminole and Polk counties.
Related Inspections
The other inspection Florida insurers ask for. Bundle both for $250.
Why insurers care about this pipe, and what to do if you have it.
See exactly what a completed 4-Point report looks like.